Key Takeaways
- Financial agreements can help couples formalise how property and financial resources will be divided if a relationship ends.
- Binding financial agreements may be made before, during, or after a marriage or de facto relationship.
- Both parties must obtain independent legal advice for a financial agreement to be legally enforceable.
- Financial agreements can help avoid court proceedings and provide greater certainty around property settlement matters.
- Poor drafting, pressure, or inadequate disclosure may increase the risk of an agreement being challenged or set aside.
Understanding financial agreements in Australia
Financial agreements can play an important role in helping couples manage property and financial matters before, during, or after a relationship. These agreements can help clarify how assets, liabilities, and financial resources may be divided if a relationship ends. We explain how these agreements work, the legal requirements involved, and the potential benefits and risks you should understand before signing one.
What is a financial agreement?
A financial agreement is a legally binding agreement made under the Family Law Act that outlines how property, financial resources, liabilities, and other financial matters will be managed if a relationship ends. Financial agreements can be entered into before, during, or after a marriage or de facto relationship and are commonly used to formalise property settlement arrangements outside of court proceedings.
Types of financial agreements in Australia:
- Section 90B agreements — made before marriage (commonly referred to as prenuptial agreements)
- Section 90C agreements — made during a marriage
- Section 90D agreements — made after divorce
- Section 90UB agreements — made before a de facto relationship
- Section 90UC agreements — made during a de facto relationship
- Section 90UD agreements — made after a de facto relationship ends
What is a prenuptial agreement, and how does it differ?
A prenuptial agreement is a type of binding financial agreement made before marriage or before entering into a de facto relationship. It allows couples to set out how property, assets, liabilities, and financial resources will be managed if the relationship ends in the future.
While all prenuptial agreements are financial agreements, not all financial agreements are prenuptial agreements, as some can be made during or after a relationship.
Common misconceptions about prenuptial agreements
- A prenuptial agreement is not only for wealthy couples: Financial agreements can be useful for many couples, including those with businesses, children from previous relationships, inheritances, or differing financial circumstances.
- A prenuptial agreement does not automatically guarantee protection: Agreements may still be challenged or set aside if legal requirements are not properly met.
- Prenuptial agreements are not only about divorce planning: Many couples use financial agreements to create financial clarity, reduce uncertainty, and formalise expectations under family law.
When should you make a financial agreement?
Financial agreements can be made at different stages of a relationship depending on the circumstances and goals of the parties involved. Some couples enter into agreements before marriage or moving in together, while others use financial agreements during a relationship or after separation to formalise property settlement arrangements and avoid future disputes.
| Timing | Why couples may use a financial agreement | Potential benefit |
|---|---|---|
| Before marriage or a de facto relationship | To protect existing assets, businesses, inheritances, or family wealth | Greater financial clarity and asset protection |
| During a relationship | To formalise changing financial circumstances or business interests | Clearer management of financial responsibilities |
| After separation or divorce | To formalise a property settlement without going to court | Provides an organised checklist of legally binding agreements |
Are financial agreements legally binding?
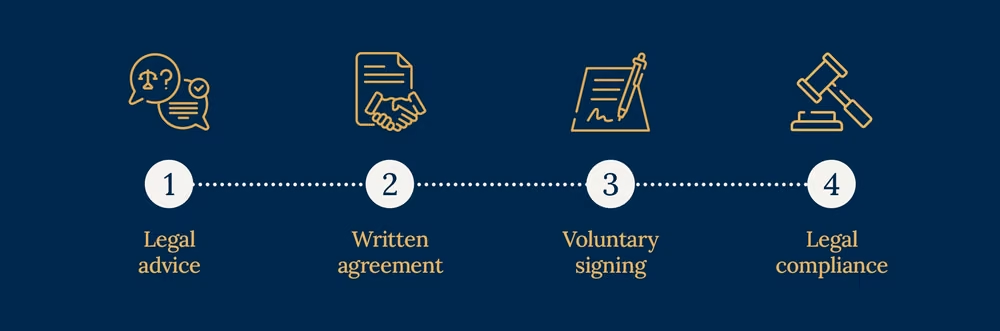
Financial agreements can be legally binding in Australia if they comply with the requirements set out under the Family Law Act. Because these agreements can significantly affect legal rights and future property settlement entitlements, strict legal requirements must be followed for the agreement to be enforceable.
- 01

Obtain independent legal advice
Each party must receive independent legal advice from their own Australian legal practitioner before signing the agreement. The advice must explain the effect of the agreement and the advantages and disadvantages of entering into it.
- 02

Ensure the agreement is in writing
The financial agreement must be prepared in writing and clearly outline how property, liabilities, superannuation, and financial resources will be managed or divided.
- 03

Both parties must sign voluntarily
The agreement must be signed voluntarily without undue pressure, coercion, or unfair influence. Both parties should have sufficient time to review the agreement before signing.
- 04

Proper legal documentation must be completed
Each lawyer must provide a signed statement confirming that independent legal advice was given. This documentation is an important requirement for the agreement to remain legally enforceable.
Benefits of financial agreements
Financial agreements can provide couples with greater clarity and control over how property and financial matters will be managed if a relationship ends. When properly prepared, these agreements may help reduce uncertainty, minimise disputes, and formalise arrangements outside of court proceedings.
Key benefits:
- Greater certainty around property and financial arrangements
- Opportunity to formalise agreements privately and outside of court
- Potential reduction in legal costs and future disputes
Protect existing assets and financial interests
Financial agreements can help protect businesses, inheritances, investments, and other financial resources that one or both parties wish to preserve in the event of a relationship breakdown.
Create financial clarity early
Discussing financial matters and expectations early can help couples better understand their respective financial circumstances and future responsibilities.
Reduce the likelihood of future disputes
A clearly drafted agreement on the division of property and financial resources may help minimise uncertainty and conflict following separation.
Formalise arrangements without going to court
Financial agreements can allow separating couples to formalise property settlement arrangements privately rather than relying on court proceedings.
Provide flexibility for different relationships
Binding financial agreements can be tailored to married couples, de facto relationships, blended families, and individuals with unique financial circumstances.
Support long-term financial planning
Some couples use financial agreements as part of broader financial and estate planning strategies, particularly where businesses, trusts, or family wealth structures are involved.
Risks and limitations of financial agreements

Poor financial disclosure
A financial agreement may be challenged if one party fails to provide full and frank disclosure about assets, liabilities, income, or financial resources. Ensure both parties exchange accurate and complete financial information before signing the agreement.
Inadequate legal advice
Financial agreements can become unenforceable if both parties do not obtain proper independent legal advice. Each party should receive advice from their own Australian legal practitioner or divorce lawyer before signing the agreement.
Pressure or unfair influence
Agreements signed under pressure, coercion, or significant imbalance in bargaining power may later be set aside by the court. Allow sufficient time for negotiation, review, and voluntary decision-making throughout the process.
Outdated agreements
Changes in financial circumstances, children, businesses, or health may affect whether an agreement remains appropriate over time. Review financial agreements periodically and obtain updated legal advice where circumstances change significantly.
Incorrect drafting or technical errors
Poorly drafted agreements or failure to comply with Family Law Act requirements can create enforceability risks. Work with experienced family lawyers familiar with binding financial agreements and family law requirements.
Assuming financial agreements cover everything
Financial agreements generally focus on financial and property matters and may not fully address parenting arrangements or child support issues. Seek legal advice about whether additional family law documents or arrangements may also be required.
Get financial agreements done properly from the start
A poorly prepared financial agreement can create unnecessary risk, uncertainty, and future disputes. Get clear, legal advice from experienced family lawyers to ensure your agreement is properly drafted, legally enforceable, and tailored to your financial circumstances.
Can financial agreements be set aside or challenged?
Although financial agreements can be legally binding, the Family Court may set aside or invalidate an agreement in certain circumstances. Courts will generally examine whether the agreement complies with the Family Law Act and whether both parties entered into the agreement fairly and voluntarily.
Financial agreements may also be challenged where there has been inadequate disclosure, unfair conduct, or significant changes in circumstances that make the agreement impractical or unjust. This is why obtaining independent legal advice and properly preparing the agreement is critical.
Examples of when agreements may be challenged:
- One party failed to provide full and frank financial disclosure
- The agreement was signed under pressure, coercion, or undue influence
- The agreement does not properly comply with legal requirements under family law legislation
How much does a financial agreement cost in Australia?
The cost of preparing a financial agreement in Australia can vary depending on the complexity of the relationship, the value of the assets involved, and whether negotiations are straightforward or contested. Factors such as businesses, trusts, superannuation, disclosure requirements, and existing property arrangements may also affect legal costs.
Because binding financial agreements require independent legal advice for both parties and careful drafting to ensure enforceability, it is important to obtain advice tailored to your circumstances rather than relying on generic templates or informal agreements.
Create certainty around your financial future
Financial agreements can help couples clarify property and financial arrangements while reducing uncertainty if a relationship ends. If you are considering a binding financial agreement or prenuptial agreement, speaking with an experienced family lawyer can help ensure your agreement is properly prepared and legally enforceable.
Table of contents